Bell County Buyers Just Caught a $3,000 Break. Here’s What That Actually Means.
By David Laws — Mortgage Loan Officer | Fairway Home Mortgage | LoanswithLaws.com | Salado, Texas | NMLS #2794754
Bell County Buyers Just Caught a $3,000 Break. Here’s What That Actually Means.
By David Laws — Mortgage Loan Officer | Fairway Home Mortgage | LoanswithLaws.com | Salado, Texas | NMLS #2794754
For the first time in three years, it’s gotten meaningfully easier to qualify for a home in Bell County.
Not by a lot. But enough to matter.
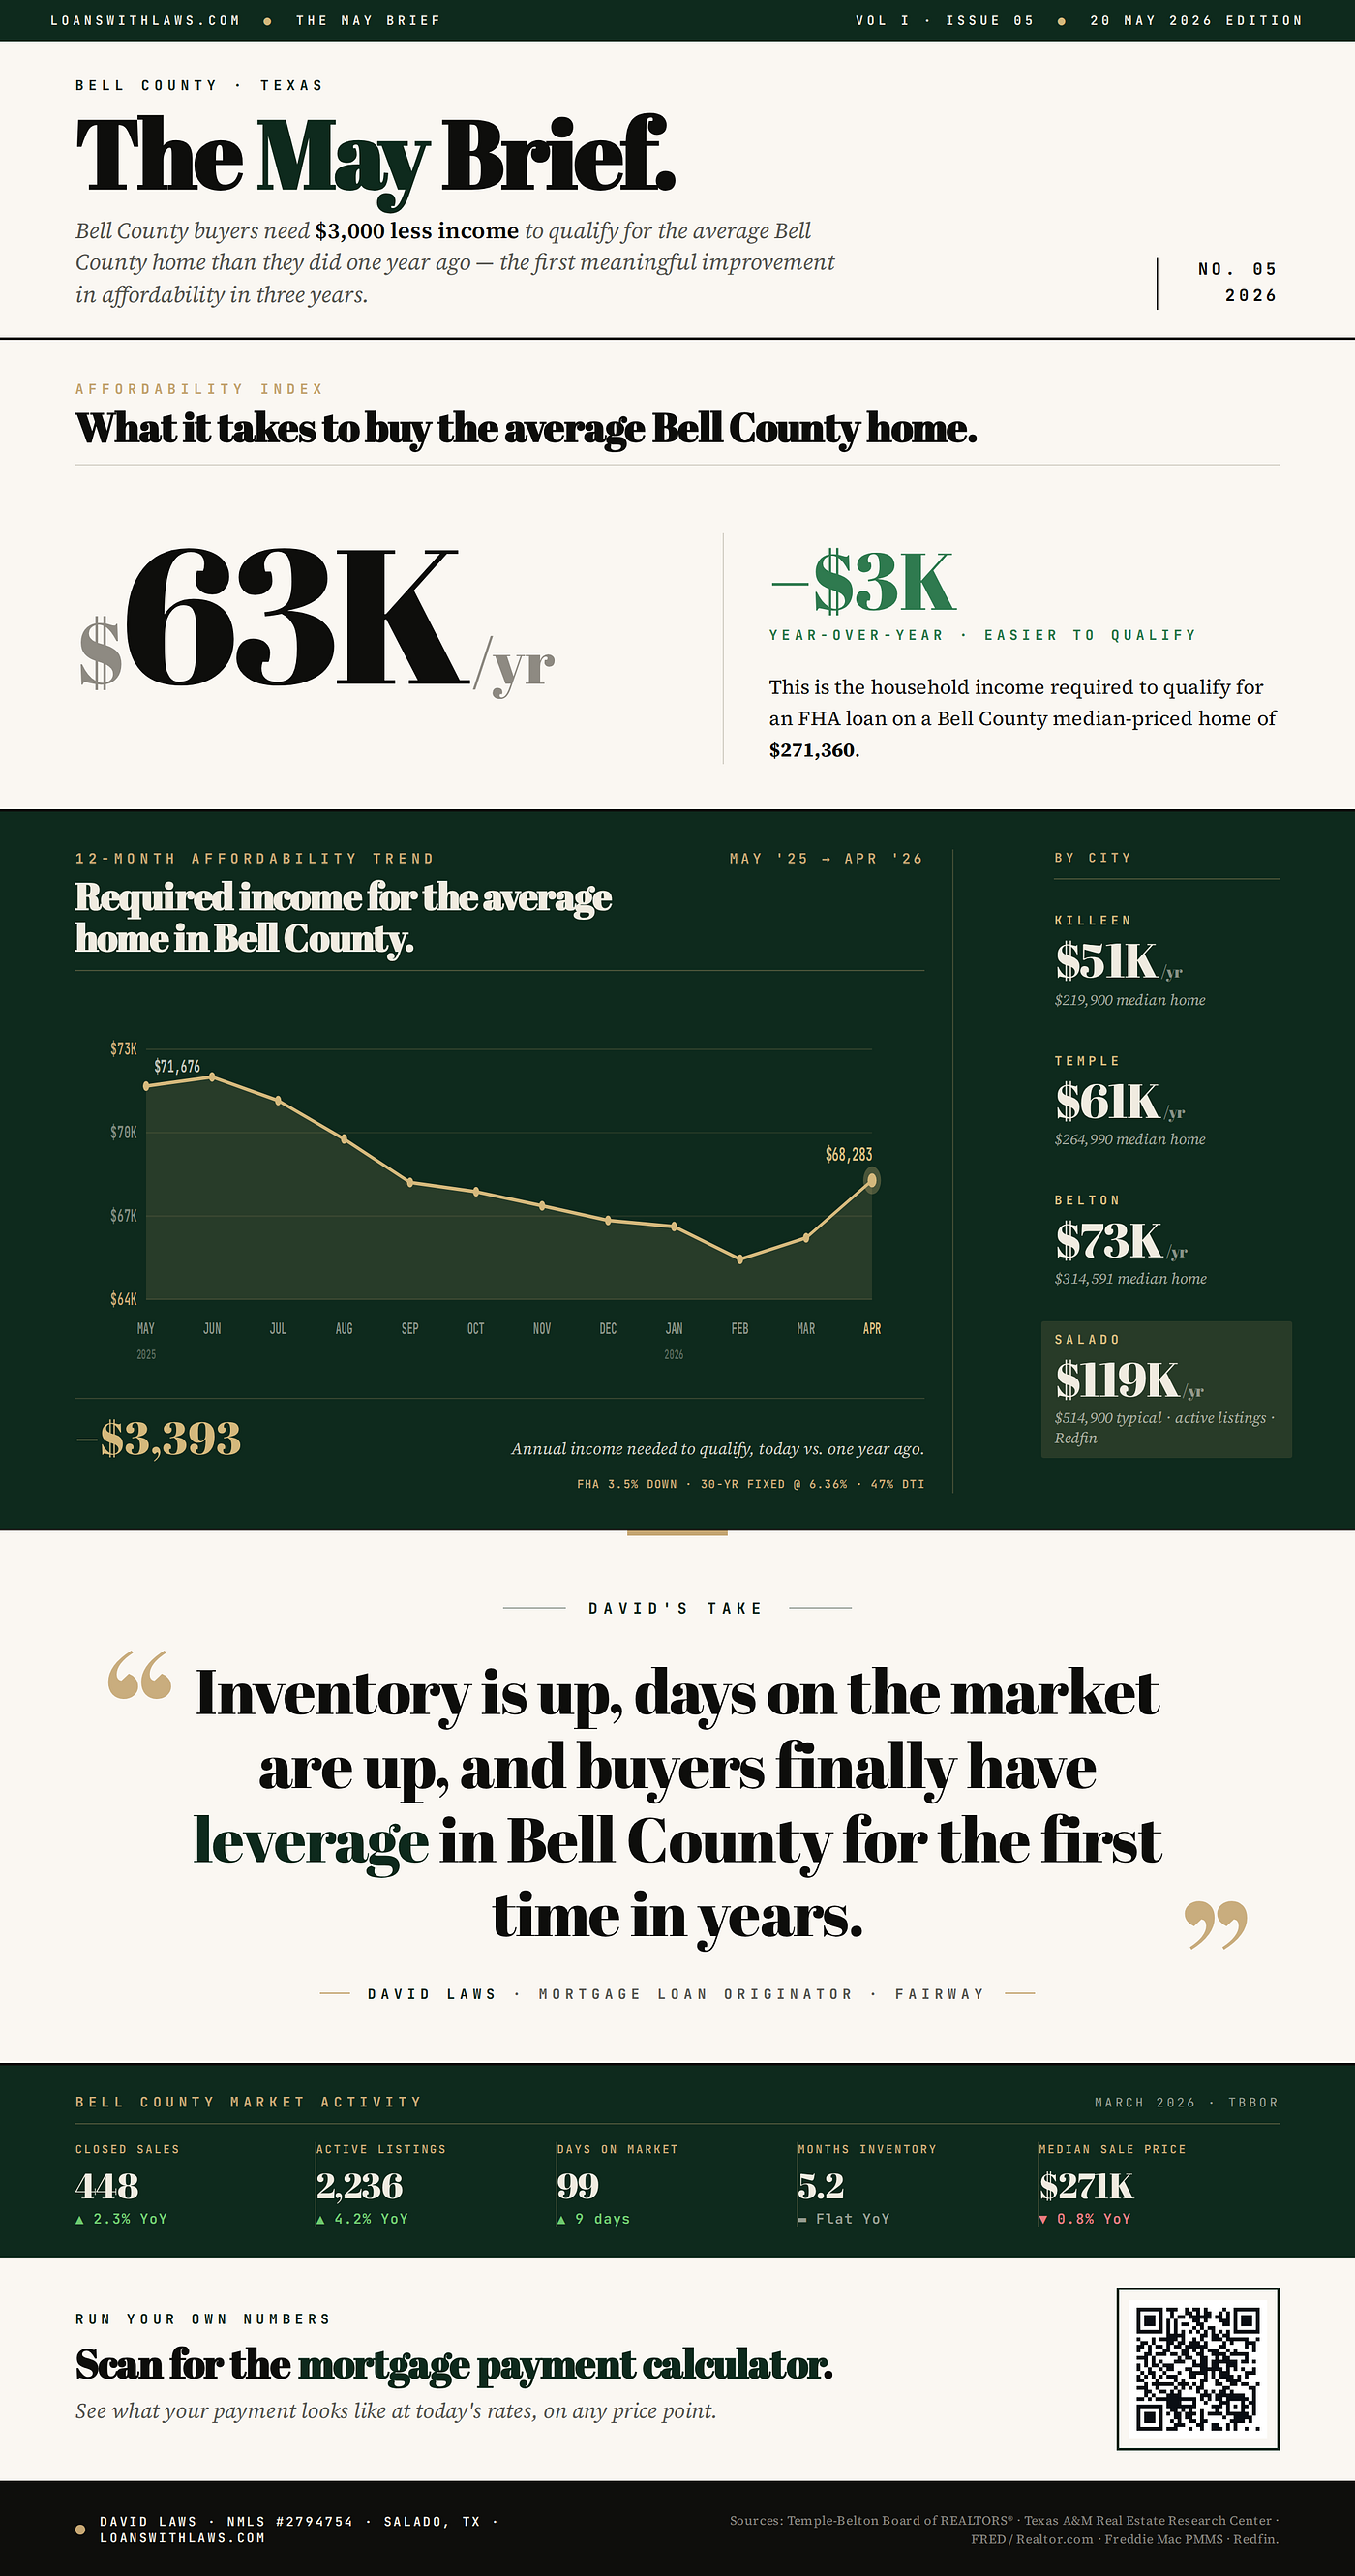
As of April 2026, the household income needed to qualify for an FHA loan on a median-priced Bell County home dropped to roughly $63,000 a year — down about $3,393 from the same time last year. That’s based on a median sale price of $271,360, a 30-year fixed FHA loan at 6.36%, 3.5% down, and a 47% DTI ceiling.
If you’ve been sitting on the sidelines wondering whether anything was ever going to shift, something finally did.
Let me walk you through what’s actually happening — and what it means depending on where in Bell County you’re looking.
The Headline Number
$63,000 a year. That’s the qualifying income on the average Bell County home today.
A year ago, it was over $66,000. In June of 2025, it peaked north of $71,000.
That’s a meaningful move. Not “the market is fixed” meaningful — but enough that buyers who got priced out twelve months ago should genuinely re-run their numbers. I’ve had three conversations in the last two weeks with families who assumed they still couldn’t qualify, ran the math again, and realized they could.
The math changed. They didn’t.
Why Affordability Improved (When Rates Didn’t)
Rates didn’t really drop. The 30-year fixed is sitting around 6.36% — not meaningfully different from where we were last spring. So if rates didn’t move, what did?
Two things:
1. Median prices softened. Bell County’s median sale price came in at $271,000 in March 2026, down 0.8% year over year. Small number, real impact.
2. Inventory grew. Active listings are up 4.2% year over year. Days on market climbed to 99 — that’s nine days longer than a year ago. Months of inventory is sitting at 5.2, which is the line between a seller’s market and a balanced one.
Translation: sellers don’t have the same leverage they had two years ago. Buyers have time to think. Offers don’t need to be aggressive to win. Inspections actually happen.
This is the first time in a long stretch where I’d describe Bell County as a buyers market.
What It Looks Like By City
Bell County isn’t one market. It’s five or six, and the spread is wide.
Killeen — $51,000/yr qualifying income. Median home around $219,900. This is where first-time buyers with modest incomes still have real options. Killeen has been the most affordable corner of Bell County for years, and the math reflects it. It’s especially affordable since many buyers in Killeen are veterans using VA loans with 0% down and no PMI.
Temple — $61,000/yr qualifying income. Median around $264,990. Temple is where a large majority of the medical and industrial community lives, and the affordability profile reflects a mid-tier income base. If you’re a nurse, a tech, a teacher, a young physician finishing residency at Baylor Scott & White — Temple is usually the conversation.
Belton — $73,000/yr qualifying income. Median around $314,591. Belton has quietly become one of the more competitive submarkets in Central Texas — UMHB families, growing school district, an attractive small downtown. The price reflects the demand. It’s also one of the most financially diverse areas in Bell County in terms of average house price.
Salado — $119,000/yr qualifying income. Typical active listing $514,900. Salado is its own thing. Lower volume, higher price points, a different buyer profile. If you’re shopping here, the affordability conversation is different — it’s usually less about qualifying and more about structure. There are very few options for first-time home buyers in the Salado market.
If you’re trying to figure out where you fit, the city matters more than the county-wide number.
What This Doesn’t Mean
A few things to be careful about.
It doesn’t mean rates are dropping. They’re not. The improvement came from prices and inventory, not from the Fed.
It doesn’t mean we’re at the bottom. Median price ticked down 0.8% — that’s a soft move, not a crash. Don’t try to time the bottom. Nobody hits it cleanly.
It doesn’t mean every house is a deal. Days on market going up is a market-wide stat. Well-priced, well-presented homes in good school districts are still moving in under three weeks. The 99-day average is being dragged up by overpriced listings sitting because sellers haven’t adjusted yet.
And it doesn’t mean qualifying is easy. $63K is the qualifying income at a 47% DTI — which is the upper end of what FHA will allow. The reality for most buyers is that you want some breathing room below that ceiling, not at it.
What I’d Actually Do Right Now
If you’re a first-time buyer in Bell County who got discouraged in 2024 or 2025, re-run your numbers. Seriously. Not next quarter. Now. The income required to qualify has come down enough that a lot of people are sitting on outdated assumptions.
If you’re a current homeowner thinking about moving up — Salado, Belton, the better parts of Temple — you’re now in a window where buyers have leverage for the first time in a while. Inspection contingencies are getting honored. Sellers are negotiating. That hasn’t been true since 2022.
If you’re shopping in the jumbo range in Salado, the structure conversation matters more than the rate conversation. There’s usually a smarter way to put the deal together. (By the way, the conforming loan limit for Bell County just increased in 2026, so luxury buyers have even mroe buying power now).
And if you’re a UMHB family, a medical professional finishing training at Baylor Scott & White, or a teacher trying to figure out whether Belton ISD is still in reach — the numbers might surprise you compared to where they were last spring.
A Word on the Data
Everything above comes from the Temple-Belton Board of REALTORS®, the Texas A&M Real Estate Research Center, Freddie Mac’s PMMS rate survey, FRED, and Redfin. The qualifying income calculation assumes FHA financing at 3.5% down on a 30-year fixed at 6.36%, with a 47% DTI threshold including taxes and insurance. If your scenario is different — conventional, USDA (which still works in pockets of Bell County), VA, jumbo — the math shifts.
Bell County data is published monthly. I track it, I write about it, and I publish a regular brief on it because clients deserve to make decisions on real local numbers, not national headlines that don’t reflect what’s actually happening between Killeen and Salado.
David Laws is a mortgage loan officer with Fairway Home Mortgage, helping families in Salado and Bell County- from first-time homebuyers to more complex purchases- create strategic homebuying plans. LoanswithLaws.com.
메타데이터
- post_id
- 50ba32abb791
- slug
- bell-county-buyers-just-caught-a-3-000-break-heres-what-that-actually-means-50ba32abb791
- url
- https://medium.com/@david.laws-bellcounty-mortgage/bell-county-buyers-just-caught-a-3-000-break-heres-what-that-actually-means-50ba32abb791
- canonical_url
- https://medium.com/@david.laws-bellcounty-mortgage/bell-county-buyers-just-caught-a-3-000-break-heres-what-that-actually-means-50ba32abb791
- author_url
- https://medium.com/@david.laws-bellcounty-mortgage
- status
- ok
- fetched_at
- 2026-06-09 15:37:30



