Trump’s Economic Rhetoric vs. Reality: Impact on Voters’ Financial Well-Being
Trump’s Lofty Economic Promises
Information Warfare — Information War
Trump’s Economic Rhetoric vs. Reality: Impact on Voters’ Financial Well-Being
Trump’s Lofty Economic Promises
Donald Trump campaigned on bold economic promises, vowing to slash regulations and cut taxes to ignite growth. His 2017 tax overhaul was billed as “rocket fuel” for the economy (americansfortaxfairness.org). Trump confidently predicted sustained GDP growth of 4%, 5%, even 6% per year (americansfortaxfairness.org), far above recent norms. He pledged a manufacturing renaissance and said workers would see big pay raises (the White House even claimed the corporate tax cut could boost average household wages by around $4,000). The overarching promise was that everyone — including his voter base of working-class Americans — would prosper like never before under these policies.
Economic Growth Falls Short of Expectations
In reality, economic growth under Trump never reached the heights he promised. After the tax cuts, real GDP growth hit about 3.0% in 2018 but then slowed to 2.2% in 2019, never exceeding 3% annually during his term (americansfortaxfairness.org). Trump’s boast of breaking the trend fell flat — the growth rate continued roughly in line with the momentum from the Obama years (presidency.ucsb.edu)(presidency.ucsb.edu). In fact, Trump’s fastest quarterly GDP growth (3.5%) was lower than several of Obama’s best quarters (presidency.ucsb.edu). By late 2019, the “boom” was losing steam: economic sugar highs from tax cuts were fading and forecasts showed growth slipping back toward ~2% (politico.com).
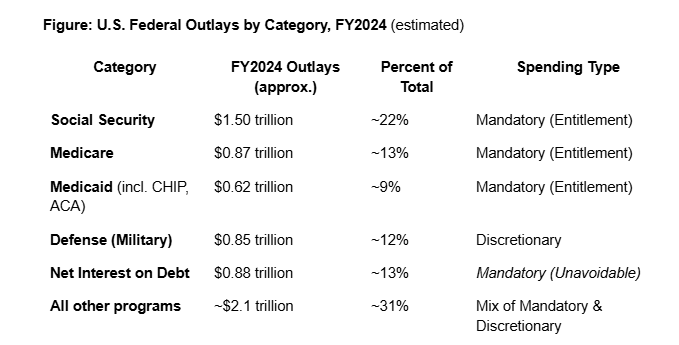
Critically, deficit-funded stimulus propped up much of this growth. The federal budget deficit surged above $1 trillion a year after Trump’s tax cuts (politico.com). This large borrowing helped juice short-term GDP but limits future flexibility, according to the nonpartisan Congressional Budget Office projections (presidency.ucsb.edu). In 2020, the disconnect between rhetoric and reality became stark. The economy was hit by a sharp contraction — real GDP shrank 3.5% in 2020, the worst annual decline since 1946 (theguardian.com). While the pandemic was the immediate cause, it wiped out the core of Trump’s economic narrative, as the “greatest economy ever” ended in a downturn.
Declining Confidence and Rising Recession Fears
Even before COVID-19, cracks in economic sentiment were showing. In mid-2019, a key warning sign flashed: the U.S. Treasury yield curve inverted, a historically reliable predictor of recession (politico.com). Wall Street analysts noted a “little bit of panic” as bond markets signaled the economy might be weaker than advertised (politico.com). The Federal Reserve, responding to “slower growth” and trade uncertainty, reversed course and cut interest rates in 2019 to sustain the expansion (politico.com). Fed Chair Jerome Powell noted that business investment had slowed, partly from concerns over trade tensions (federalreserve.gov)– a direct fallout of Trump’s trade policies.
Meanwhile, consumer confidence — a gauge of Main Street’s outlook — started to wobble. By August 2019, Americans’ optimism took a dive: the University of Michigan’s consumer sentiment index recorded its largest monthly drop since 2012, plunging from a reading of 98.4 in July to 89.8 in August, the lowest since October 2016 (markets.businessinsider.com)(markets.businessinsider.com). Researchers attributed this decline to “negative references to tariffs” and mounting recession fears in survey responses (markets.businessinsider.com)(markets.businessinsider.com). In other words, Trump’s trade war with China was “torpedoing” consumer confidence, as one analysis put it, and even the White House’s tariff delays couldn’t fully reassure nervous consumers (politico.com)(politico.com). Such dips in confidence matter: when households grow anxious, they spend less, which can further slow the economy in a self-fulfilling cycle.
Tax Cuts Enriched Corporations More Than Workers
Trump’s signature Tax Cuts and Jobs Act delivered a hefty windfall to corporations and the wealthy, but the promised broad-based benefits to workers were muted. Rather than unleashing an investment and wage boom, much of the corporate tax savings went into stock buybacks and shareholder payouts. U.S. companies in the S&P 500 spent an unprecedented $806 billion on stock buybacks in 2018, shattering the previous record (around $590 billion in 2007) (apnews.com). This rewarded shareholders (who are disproportionately upper-income) and boosted the stock market, but the direct pay-off to the average worker was limited.
To be sure, the economy did continue adding jobs through 2019 and unemployment hit a 50-year low at one point. However, the pace of job growth actually slowed under Trump compared to the late Obama era. In Trump’s first three years (before the pandemic), employers added an average of 193,000 jobs per month — below the 224,000 per month average in Obama’s last three years (presidency.ucsb.edu). Wage growth did inch up in the tight labor market, but far from the $4,000 raises touted. By early 2020, real wages for typical workers were only growing modestly above inflation, and income inequality widened — the Census Bureau reported inequality was “significantly higher” in 2018 than in prior years (presidency.ucsb.edu). In short, Wall Street reaped much of the upside (via higher stock values and dividends), while many working families saw only incremental gains.
Real Impacts on Trump Voters’ Wallets
Trump’s core supporters — including blue-collar workers and rural Americans — felt the pinch of these economic realities despite the glowing rhetoric. For example, the promised factory revival faced headwinds. Amid trade disputes and slowing demand, the manufacturing sector stumbled in 2019, and job gains stalled. In the crucial Rust Belt states that helped elect Trump, factories actually shed about 36,000 manufacturing jobs in 2019, erasing some earlier gains (presidency.ucsb.edu). This downturn hit exactly the communities Trump vowed to uplift, contributing to lost income for industrial workers. Factory layoffs and reduced hours undercut the claim that deregulation and tariffs had **“brought back” manufacturing on a sustainable basis.
Farmers — another key Trump constituency — were hammered by the trade war. China’s retaliatory tariffs on U.S. agricultural products sharply reduced American farm exports. As one Wall Street analysis noted, the “loss of the Chinese market” dealt a heavy blow to farmers, creating financial stress on farms across the heartland (politico.com). The Trump administration had to authorize tens of billions in emergency farm bailouts to offset these losses, meaning taxpayers footed the bill for a trade policy debacle. Despite this aid, farm bankruptcies rose in some regions, illustrating how trade policy uncertainty directly hurt rural livelihoods.
Beyond specific sectors, many American households remained on shaky financial footing. The Federal Reserve’s own surveys show that even during the pre-pandemic “high” of Trump’s economy, one-quarter of U.S. adults had no retirement savings or pension at all (federalreserve.gov). Millions also lived paycheck to paycheck with minimal emergency savings. The number of people without health insurance increased under Trump, reversing previous gains, which left more families one illness away from financial ruin (presidency.ucsb.edu). These trends hit low- and middle-income folks hardest — including many Trump voters in working-class and rural areas. In other words, the aggregate economic numbers masked the fact that a large share of Americans were not feeling particularly “great again” in their personal finances.
State and Local Taxes
During his 2024 campaign, former President Donald Trump pledged to repeal the $10,000 cap on state and local tax (SALT) deductions, a limit that was introduced under the 2017 Tax Cuts and Jobs Act (TCJA) during his previous administration. This cap has been a point of contention, particularly among residents of high-tax states such as New York, New Jersey, and California, where taxpayers often pay substantial state and local taxes.
Potential Outcomes of Eliminating the SALT Cap:
- Beneficiaries: Repealing the SALT cap would predominantly benefit higher-income taxpayers. The Tax Policy Center estimates that the top 1% of earners could see an average tax reduction of approximately $35,000, accounting for about 43% of the total benefit from lifting the cap. taxpolicycenter.org+1taxpolicycenter.org+1
- Federal Revenue Impact: The Committee for a Responsible Federal Budget projects that eliminating the SALT cap could reduce federal revenue by an estimated $1.2 trillion over a decade. This significant decrease in revenue raises concerns about increasing the federal deficit. kiplinger.com
- Geographic Implications: Taxpayers in high-tax states, such as New York, New Jersey, and California, would experience the most substantial benefits from the repeal, as they typically incur higher state and local taxes. marketwatch.com
- Economic Considerations: Proponents argue that eliminating the SALT cap could stimulate economic activity in high-tax states by reducing the overall tax burden on residents, potentially encouraging investment and spending. However, critics contend that the repeal would primarily advantage the wealthy and exacerbate income inequality.
- Political Dynamics: The debate over the SALT cap repeal reflects broader discussions about tax equity and fiscal responsibility. While some lawmakers from high-tax states advocate for the repeal to alleviate their constituents’ tax burdens, others express concern about the fiscal implications and the distribution of benefits skewed towards higher-income individuals.
President Trump’s commitment to eliminating the SALT cap aligns with his broader tax policy objectives but presents challenges in balancing tax relief with fiscal responsibility. The proposal’s success depends on legislative negotiations and the ability to address concerns regarding federal revenue loss and equitable benefit distribution.
Conclusion: Rhetoric vs. Reality and the Road Ahead
Donald Trump’s economic narrative painted a picture of unprecedented prosperity, but the data tell a more sobering story. Yes, the economy continued expanding through most of Trump’s term, but growth never broke out of the modest range seen in prior years (americansfortaxfairness.org). Deficit-funded tax cuts did not unleash the predicted investment supercharge; instead, they swelled the debt and largely benefited corporations and investors (apnews.com). By 2019, warning signs — from cooling GDP and business investment to sliding consumer confidence — contradicted the “boom” narrative (politico.com)(markets.businessinsider.com). The ultimate reality check came in 2020, when the expansion collapsed into a recession, leaving millions of Americans jobless.
For voters, especially those who supported Trump in hopes of economic betterment, it’s crucial to separate political spin from economic facts. The evidence suggests Trump’s policies delivered a mixed bag: corporate profits and the stock market surged, but many workers saw limited gains, and some were worse off (due to job losses in farming and manufacturing, or lost insurance coverage). Knowing these facts empowers voters to hold leaders accountable. Economic policy is complex, and results often diverge from rosy promises. As the Federal Reserve and independent analysts have documented, sustainable growth stems from sound fundamentals, not just tax cuts or tariffs (politico.com). Equipping oneself with these realities — GDP trends, confidence indices, job and income data — helps cut through the hype. In the end, informed voters can demand policies that truly improve their financial well-being, rather than settle for rhetoric that rings hollow when paychecks and savings are on the line.
Sources: Recent analyses and data from the Federal Reserve, Bloomberg Economics, and Wall Street experts were used to compare Trump’s economic promises with outcomes (americansfortaxfairness.org)(politico.com)(markets.businessinsider.com)(presidency.ucsb.edu). These fact-based assessments reveal the gap between the rhetoric of “the best economy ever” and the real economic challenges many Americans faced under Trump’s policies.
메타데이터
- post_id
- 6f457861736d
- slug
- trumps-economic-rhetoric-vs-reality-impact-on-voters-financial-well-being-6f457861736d
- url
- https://money-politics.com/trumps-economic-rhetoric-vs-reality-impact-on-voters-financial-well-being-6f457861736d
- canonical_url
- https://money-politics.com/trumps-economic-rhetoric-vs-reality-impact-on-voters-financial-well-being-6f457861736d
- author_url
- https://medium.com/@hase_fiero
- status
- ok
- fetched_at
- 2026-06-14 11:28:49