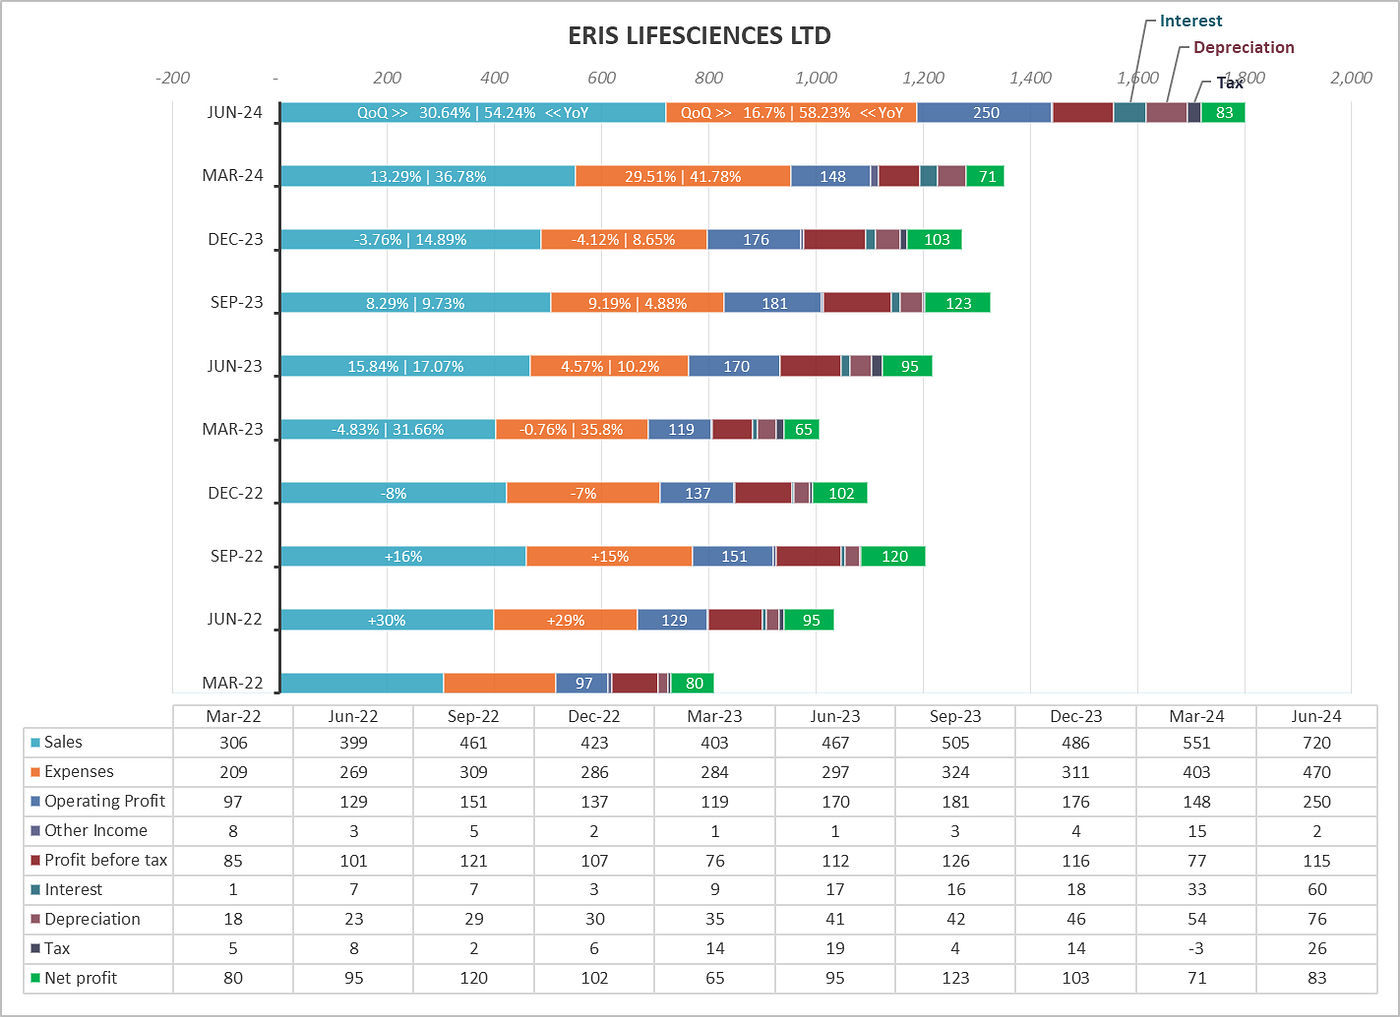
Eris Lifesciences Q1 FY25 Earnings Call Summary
Earnings Call Transcript can be found here
Eris Lifesciences Q1 FY25 Earnings Call Summary
Earnings Call Transcript can be found here
Key Takeaways
Positives:
-
Revenue Growth and Market Position: — The company’s Domestic Branded Formulations (DBF) segment grew by 12.7% in Q1, significantly outpacing the covered market growth of 8.1%. — Eris now ranks among the Top 20 companies in the market, climbing nine ranks since its IPO in 2017. — The Biocon-1 and Biocon-2 segments, acquired recently, are showing strong growth. Biocon-1 saw a 16% revenue growth in Q1 with significant margin improvements, while Biocon-2 grew by 13% with potential for further margin expansion.
-
Margin Improvement: — Gross margins improved significantly in multiple segments: — Base business: Gross margin up by 300 bps to 86%. — Biocon-1: Gross margin up by 1,500 bps to 65% post-acquisition. — EBITDA margins also saw substantial growth: — Base business EBITDA margin improved by 185 bps to 39%. — Biocon-1 segment’s EBITDA margin jumped from 19% at acquisition to 39%.
-
Strategic Acquisition: — The acquisition of the Loan License (LL) manufacturing site in Bhopal is a strategic move that will enhance the company’s biotech capabilities, particularly in insulin and GLP segments. The acquisition is expected to reduce time to market by two years and immediately improve margins in the insulin segment by 1,000 bps.
-
Strong Guidance and Growth Outlook: — The company is guiding for strong revenue growth across segments: — DBF revenue of Rs. 2,600 crores with a 36% EBITDA margin. — Biocon segments are expected to deliver 27% revenue growth with a margin expansion of 1,000 bps. — Swiss Parenterals revenue of Rs. 330 crores with a 35% EBITDA margin.
**5. Strong Revenue Base and Margins:
- **The company expects a solid revenue base of Rs. 1,850 crores for FY24 with an EBITDA margin of 37%. This suggests a stable and profitable core business.
- The company anticipates significant margin improvement driven by productivity gains, gross margin enhancement, and fixed cost synergies.
6. Focus on High Growth Areas: -The company is expanding into high-value areas like Insulins, GLP1s, MABs, and hormones, which are considered high entry barrier businesses with good growth potential.
**7. Operational Efficiency and Expansion:
- **There is an ongoing ramp-up in the Ahmedabad plant with a 70% increase in throughput while keeping operating cost growth minimal. This is expected to reduce unabsorbed fixed costs significantly by Q4.
8. Cost Control and Debt Reduction: -The company is maintaining a disciplined approach to capital expenditure and is focusing on debt reduction. Even with Rs. 120 crores allocated to internal capex, debt is expected to reduce to Rs. 2,600 crores or lower by year-end.
9. Tax Efficiency: -The company is planning to optimize its tax rate, gradually lowering it from 25% to 18% over the next few years as it ramps up operations in the new plant.
Negatives:
1. Cardiac Portfolio Underperformance: — The Cardiac portfolio has been underperforming compared to the Indian Pharmaceutical Market (IPM) for several years, with a significant impact from the underperformance of the brand Zayo.
2. Gross Margin Decline in DBF Segment: — The DBF segment experienced a gross margin reduction of 600 bps in Q1 due to a change in product mix following the Biocon acquisitions.
3. Debt Levels: — The company’s net debt as of June 30th stood at Rs. 2,700-plus crores, though there are plans to reduce this to Rs. 2,000 crores by fiscal ‘26.
**4. Dependence on External Manufacturing:
- **A shift from 80% to 60% in-house manufacturing, particularly due to the Biocon acquisition, could impact margins and increase operational complexity.
**5. Delayed Benefits from New Acquisitions:
- **The company’s acquisition strategy, while promising, may take 3–4 years to fully realize benefits, particularly due to the time required to obtain necessary licenses and ramp up operations.
6. Operational Risks and Execution Challenges: -The management acknowledged potential challenges in executing the large-scale expansion into biotechnology and specialty pharmaceuticals, which could pose operational risks.


Price Action
- +8% since results 2nd Aug 2024
- +33% YTD
- +45% 1 Year
Top Heuristic Metrics to Monitor
Revenue Growth Relative to Market:
- The company’s Domestic Branded Formulations (DBF) segment outpaced the market with a 12.7% growth compared to the market’s 8.1%. This is a strong indicator of Eris Lifesciences’ ability to capture market share and grow faster than its peers. Revenue growth, especially when it exceeds market growth, is a key metric in assessing the company’s competitive positioning and overall business momentum.
Margin Expansion:
- The improvement in both gross margins and EBITDA margins across different segments (e.g., Base business gross margin up by 300 bps to 86%, Biocon-1 EBITDA margin improvement from 19% to 39%) is crucial. Margin expansion is a direct indicator of operational efficiency, pricing power, and successful integration of acquisitions. The ability to enhance margins, particularly in newly acquired or strategic segments like Biocon, demonstrates the company’s potential for profitability and scalability.
메타데이터
- post_id
- a681a21c98be
- slug
- eris-lifesciences-q1-fy25-earnings-call-summary-a681a21c98be
- url
- https://medium.com/@freevest/eris-lifesciences-q1-fy25-earnings-call-summary-a681a21c98be
- canonical_url
- https://medium.com/@freevest/eris-lifesciences-q1-fy25-earnings-call-summary-a681a21c98be
- author_url
- https://medium.com/@freevest
- status
- ok
- fetched_at
- 2026-06-20 20:29:01