Lighter $LIT TGE: Base, Bear, Bull scenarios
Lighter $LIT TGE on Dec 30?
Lighter $LIT TGE: Base, Bear, Bull scenarios

Lighter $LIT TGE on Dec 30?
While the market waits for a potential Lighter token launch, we break down what actually matters: airdrop mechanics, valuation ranges, and what’s already priced in.
This is our base, bear, and bull case analysis 🧵
I. Overview of Lighter
Lighter is a decentralized perpetuals DEX built as a zero-knowledge rollup on Ethereum, optimized for high speed, throughput, and scale. It currently operates with zero fees to attract users, focusing on perpetual contracts, forex, commodities, and upcoming spot markets.
Lighter has generated significant traction and is known as Hyperliquid’s biggest competitor now.
II. What we know for now
1. Tractions:
- TVL: $1.4B
- Perps volume (30d): $233.17B
- Revenue (annualized): $138.61M
- 30d revenue $11.36M
- Users: 640K+
2. Funding:
Raised $68M at a $1.5B valuation, from top investors including Founders Fund (Peter Thiel), Ribbit Capital, Haun Ventures, a16z, Dragonfly, and Robinhood
3. Speculation side:
- Coinbase added it to its listing roadmap on December 14, 2025
- TGE is speculated for December 29th, 2025
4. Tokenomics
- Token ticker: $LIT
- Total supply: ~1B tokens (consistent across multiple sources)
- Circulating supply at TGE: If mirror HYPE launch then its gonna be 30–33%, including the airdrop. This is from community rumors
- Points system: ~12M total points distributed across two seasons:
‒ Season 1: Jan-Sep 2025, ~100K users ‒ Season 2: Oct-Dec 2025, ~540K users ‒ This implies ~25 tokens per point at 30% airdrop (300M tokens / 12M points)
III. Valuation
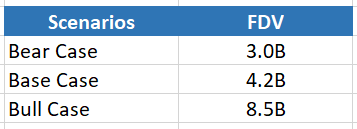
Base case: $4.2B FDV
Since Lighter is widely seen as a direct competitor to Hyperliquid and Aster, the most basic and realistic way to value it is by benchmarking against these 2 peers.

From the table comparing FDV-to-volume and FDV-to-fee multiples of Hyperliquid and Aster, it’s clear that Hyperliquid trades at a much higher premium.
That premium makes sense given its strong catalysts:
- It has an L1 ecosystem on top of the core perp product, with 1B+ TVL
- It was the first mover in this category
- It has a very strong community with high conviction
- It runs large buybacks funded by real revenue
None of these apply to Lighter or Aster. Because of that, using Hyperliquid’s multiple would overstate Lighter’s value. Aster is the more appropriate base case, so I only use Aster’s multiples to estimate Lighter’s FDV.
Based on that:
- Valuation based on volume: ~6.8B
- Valuation based on fees: ~1.6B
Taking the average, I get a fair value of around 4.2B FDV for Lighter, which align with the premarket price currently being traded on Hyperliquid ~ 4B.

Bear case: $3B FDV
Despite the strong stats, market sentiment around Lighter is a bit bearish, mainly due to the recent weak market and several bad TGEs. This is also reflected on speculative pre-market platforms.
On Polymarket, odds show a strong “Yes” for >2B, a strong “No” for <4B, and roughly 33% odds around 3B. That suggests the market is also anchoring near 3B.

Overall, market expectations seem to be pricing Lighter at around 3B FDV.
Bull case: $8.5B FDV
From the past performance, HYPE got 6x in a week after TGE.

ASTER got 4x in a week after TGE.

Because of these reasons:
- Few retailers knew about Hyperliquid and its huge potential at first. And it’s the first project using the strategy: listing its own token on its own platform only.
- Demand for HYPE was big as there were no VC rounds, and no CEX listing
- Similarly with Aster, which had relatively low attention at first and only truly exploded after CZ started shilling
For Lighter, the market is already very aware that the token is coming and pretty much everyone knows the key stats. Because of that, it’s unlikely LIT will see the kind of surprise upside we’ve seen in some past TGEs. Most of the good news is already priced in.
That said, if Lighter manages to deliver any unexpected catalysts, we could see the FDV trade at a higher premium, things like:
- Lighter sharply increases volume after the TGE. This what happened for Hyperliquid, keep $HYPE growing
- Monetization rises modestly (example: they increase the fee % ) without killing volume. As Lighter has been living with a really cheap fee, if it announces a new fee set, valuation will peak.
- Token design routes a meaningful share of protocol economics to tokenholders (buyback/burn or staking claim). Which can affect prices sharply.
Then, instead of taking Aster multiple, I will take average multiple of Aster + Hyperliquid to get the new premium valuation for Lighter. Which is 8.5B as the follow table:

So overall, these are the cases for the valuation of Lighter.
Conclusion
Based on current metrics, Lighter appears fairly valued at current market expectations.
For $LIT to outperform, Lighter needs post-TGE execution — higher volumes, stronger monetization, or clearer value capture for tokenholders.
Otherwise, the base case remains the most realistic scenario.
Research conducted by MONOLITH team! Thanks for reading this far.
Subscribe to our socials for more alpha: X, LinkedIn. Website: https://monolith.vc/
메타데이터
- post_id
- cc2da5f8130b
- slug
- lighter-lit-tge-base-bear-bull-scenarios-cc2da5f8130b
- url
- https://medium.com/@monolith.vc/lighter-lit-tge-base-bear-bull-scenarios-cc2da5f8130b
- canonical_url
- https://medium.com/@monolith.vc/lighter-lit-tge-base-bear-bull-scenarios-cc2da5f8130b
- author_url
- https://medium.com/@monolith.vc
- status
- ok
- fetched_at
- 2026-06-23 17:05:31



