Retirement: Is money everything?
In newsletter Issue [#007], we’ve covered Purpose & Structure in Retirement, and how it can be MORE important to a happy retirement than…
Retirement: Is money everything?

In newsletter Issue [#007], we’ve covered Purpose & Structure in Retirement, and how it can be MORE important to a happy retirement than how much money we’ve saved.
How could that be?
Doesn’t knowing how much money we’ve saved determine WHEN we can retire?
That’s certainly the common belief today.
In fact, we’ve seen couples where the husband worked until he dropped, saving in his retirement account to build it up so he’d “feel comfortable” in retirement!
Did he NEED the money to retire? Actually, NO! But he said he didn’t feel “comfortable” about them having enough.
Fact?
There was enough to sustain them until over 100, but at 79, he had not found a “purpose” for his retirement, so he worked. Why? It gave him purpose, structure, and a feeling that he mattered.
He kept promising his wife he would retire “next year”, but he literally died at his desk.
His wife is left with more money than she ever dreamed of having, but she is also wanting the “good times” with him she had always looked forward to in retirement, which never happened.
This is why we talk about how important it is to PLAN not only financially for retirement…but also for that “Second Act” to fulfill the remaining quarter of our lives.
The “second act” in theater is when goals are reached, relationships flourish, and people find meaning before it’s time to leave the stage.
A “Second Act” in retirement visions a purposeful, active, and creative phase, moving beyond traditional rest to new passions, careers, or “ramp-up” projects.
How do we know we’re ready for a “Second Act”, that the money is NOT going to be the issue in retirement?
Lifestyle!
Retirement is all about maintaining or creating a lifestyle that makes YOU happy. Once we KNOW the lifestyle (with purpose) we’re looking forward to, we can determine the income and assets we need to enjoy it.
Can you plan a trip’s roadmap when you don’t know the destination? Most people today do just that…plan a roadmap to retirement without knowing the destination!
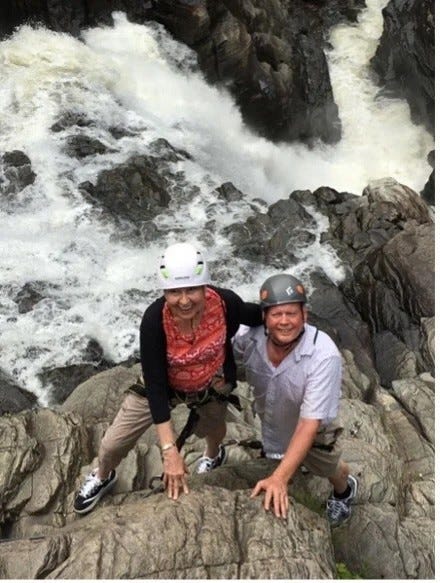
My Husband and I are climbing in Canada.
This becomes a tricky plan when we’re married! Have you sat down with your spouse to discuss what he/she wants in retirement?
My husband wanted to travel, and I wanted adventures and activities. We combined them both in our trip to Canada. (Even though he didn’t know I signed him up for the climb!). It’s best to know NOW if your idea of what retirement should look like is vastly different from your spouse’s idea.
One couple in our practice had very different ideas, and are living out retirement happily, but differently. He traveled a lot for work while she stayed home. Her idea of a great retirement is…traveling!
His idea of a great retirement is staying home. She has traveled with friends to many destinations, some exotic! He has stayed home, making small improvements to their home, and enjoying time with friends locally.
How did this affect their planning? He savors being home alone when she’s enjoying time with friends, traveling all the places she’s dreamed of.
They enjoy each other even more when together. He’s fulfilled by his friends and hobbies, she has travel tales to tell…
That lifestyle meant we needed to know how costly her travel would be. Alone, but with a friend, meant half the cost of them both traveling. Quite doable on their retirement income. How does that go? “Happy wife, happy life!” is what they say.
What is YOUR plan?
Have you and your significant other discussed what you both would like to do for a “happy retirement”? Maybe you “love gardening”, but your spouse hates being outside?
First, we determine the desired lifestyle, THEN what it will take to support that lifestyle in retirement. The income and assets you need in retirement will be determined by your goals, the very step most pre-retirees, AND their advisors, skip while discussing retirement.
We read all the time that retirees should plan on 70% to 80% of their pre-retirement income to maintain their current lifestyle. The 70%-80% rule of thumb accounts for reduced expenses such as commuting, lower taxes, and no additional retirement savings contributions.
Does the “rule of thumb” of 70% — 80% apply to your retirement?
It depends! (My favorite answer, because everyone is different!)
If you’ve been earning $150,000 a year, while saving the max $30,000 in your 401(k) or TSP, and…
- Your home is now paid off, mortgage-free,
- You have no credit card debt
- No outstanding loans on vehicles, home improvements, etc., AND
- You have $50,000 in the bank for an emergency fund,
You may only need 50% — 60%. However, we need to know what the “ lifestyle “ is that you are aiming for in retirement.
Have you considered how much of your retirement income will come from Social Security? For You? Your spouse?
Surprise, for higher earners (and we DON’T mean millionaires, SSA made it official…

https://www.ecoportal.net/en/ssa-makes-it-official-collect-5000/8285/
What would you have to do to collect this windfall of over $5,000/mo. for life?
1st: Delay until age 70 to collect.
2nd: If you contributed to Social Security
- For 35 years (and haven’t MOST of us?)
- Earned as much or more than “Contribution and Benefit Base “ between 1937–2026
- You’re a WINNER!
Here’s just a partial snapshot of those amounts. For the full table, click the link below…

https://www.ssa.gov/oact/cola/cbb.html
Have you factored in your spouse’s Social Security? That gets tricky…(We’ll address this in future newsletters)
If you have accomplished all the factors in the previous list BEFORE retirement, (no debt + Emergency Fund), you’re obviously “living within your means”! You’re not the type to go “hog wild” and wind up in debt.
If your goal is to maintain your current lifestyle, with just a few added expenses for hobbies or occasional travel, your planning will look quite different from that of our client, who went into an RV place to purchase toilet paper for his RV and came out with a new $150,000 RV!
We knew his penchant for large “spur of the moment” purchases and had to plan accordingly so he could afford the necessities in retirement.
We’ll go into the financial part of retirement in future issues.
Let’s get down to the nitty-gritty…
What is YOUR plan for your “Second Act”? What do YOU want in retirement? What does your spouse want in retirement? Have you planned a “purposeful retirement”, or will you just spend money for those “moments of happiness” we talked about in issue [#007]?
Those “moments of happiness” we often feel when we purchase something we really didn’t need or want that badly, or a gift to a grandchild, can become ongoing “moments of regret”!
Have you heard “money doesn’t buy happiness”? Spending money often buys not just moments of regret, but a lifetime of regret.
We don’t need to spend on “moments of happiness” when we’re truly happy with our lives, our “Second Act”.
What is the point of the first half of this newsletter?
If you haven’t read Issue [#007], PLEASE go back and read it NOW! This is the key to your retirement planning!
To help you plan a “purposeful” retirement, so that we can go on to plan the finances in retirement, take advantage of our gift to you…

The Center For Retirement Readiness:
https://retirepluggedin.thecenterforretirementreadiness.com
If you have a financial advisor who hasn’t spoken with you about your “Second Act”, how can they plan the finances in your retirement?
If you’ve never considered this, you think you’ll “figure it out when you get there”, you could be headed for a very rude awakening!
We’ve all been so busy living our lives, we rarely PLAN our lives, especially retirement. So, really, how DO we find out what we want in retirement besides leaving our job?
Visualize and List Your Lifestyle Goals (“Wants”)
Let’s look at the type of goals you might want in retirement.
There are so many things we’ve never had time for that we now want to do! From traveling, to spending more time with the grandkids, to developing a hobby, starting a business, or maybe just taking a daily nap!
Today, we’re going to cover just the most important goals most of us need to consider:
How do I stay physically and mentally vigorous to enjoy my OTHER goals in retirement?
To remain physically vigorous involves more than sitting on the couch…
Exercise:
For some, it’s something they don’t look forward to! Others really enjoy an exercise routine.
Now is the time to discover what YOU would do for exercise, if you could do anything you wanted to!
Remember Mom’s sage words, “Use it or Lose It!”
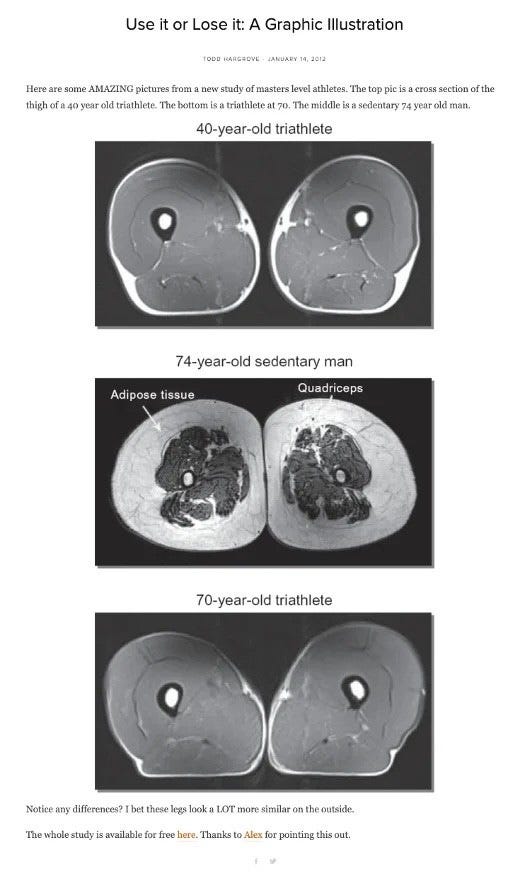
https://www.bettermovement.org/blog/2012/use-or-lose-looks-like
Maybe you would enjoy going to a gym every day, making new friends there, and setting a time for it (like my son!).
Or maybe that’s just NOT you… But (like my husband), you really like walking on the treadmill while watching your latest Netflix series! Either way, set a schedule!
Perhaps you and your spouse take a walk together every afternoon, discuss your day, and, hopefully, chat with neighbors.
Or your pup really loves your retirement because you walk him more than once every day on a schedule that HE knows and will remind you, “It’s time to go!”
Some retirees become very serious about body development or slimming down routines, but what is YOUR goal?
If your goal is simply healthy aging, there are other avenues you can pursue.
Maybe, like me, you exercise with your hobby…for me it’s gardening! Digging in the dirt, carrying bags of mulch, I bend, lift, stoop, and reach up.
For those who want to exercise, but NOT spend a lot of time, I’d look into something I’ve used for over a decade… a “Whole Body Vibration” (WBV) machine.

Me Balancing on WBV

Hubby Walking with Netflix
WebMD discusses the benefits of WBV:

https://www.webmd.com/fitness-exercise/vibration-plates
Using a Whole Body Vibration machine for as little as 15 minutes, 3 times a week (of course, more days are better!) can improve muscle strength, increase bone density (for us women!), enhance circulation, and improve balance to help you avoid falls (the greatest danger for even healthy elderly people!).
The University of Rochester’s research on falls shows:
https://www.urmc.rochester.edu/news/story/for-elderly-even-short-falls-can-be-deadly
So what do you do with this machine to enhance your strength, health, etc.? YouTube offers a myriad of WBV machine exercise videos for a variety of goals.
You can stand, and just hold on, do squats, leg lifts, and much more to exercise all parts of your body. Many have a stand with handles, as well as straps with handles for balance. (See picture of me above!)
It doesn’t matter which brand you purchase, but I highly recommend a version for retirees that has handles to hold onto. Whole Body Vibration has been shown to increase mobility and balance, even for some in their 90s!
Again, SET A SCHEDULE!
Staying physically vigorous allows us to enjoy any activity we can dream up!
Avoiding Mental Decline:
Do you want to plan some trips? Learn that hobby you’ve thought about for years? Start another career? We’ll talk about those goals in the next issue [#009].
Remember, those goals require a physically active and mentally acute individual.
Why?
Planning a trip that fulfills your goals requires internet research, attention to the details of offers, costs, timing, etc. Then you must be physically able to walk that trail to the waterfall, or participate in the activities offered.

Today, we’ll address not only staying physically vigorous but also mentally. Do you have a relative suffering from Alzheimer’s or dementia? Or maybe even a friend you’re concerned about?
Have you secretly worried that your forgetfulness of where your keys are, why you went into the other room, or the doctor’s appointment you missed, is a sign of mental decline?
It probably isn’t mental decline…As I tell my clients, by the time you get to our age, you’ve accumulated 60 years of information. Your brain is too full to hold any more!
Maybe you need to empty some of those thoughts or ideas onto paper? Just joking, but truly it helps!
How do you avoid or slow down the normal forgetfulness that creeps up with age? (Did I say normal? YES, it is normal, it doesn’t necessarily mean Alzheimer’s or dementia!)
Just as we talked about exercising our bodies, our brains need exercise too!
And YOU get to choose the exercise! Do you like crossword puzzles? Sudoku? Chess? Memory puzzles? Maybe none of those are “your thing!”
Why not try something new? Games online and in apps are not just for the kids! There’s a wonderful site to give you ideas…

https://www.gamesforthebrain.com/
There’s no doubt something in there will “ring your bell”!
Aside from mental exercise, there are other proven ways to stimulate your brain, and assist in avoiding decline.
Are you familiar with “Red Light Therapy”?
Many have learned of its benefits for healing the body, for muscle pains, arthritis, etc.
But even those who may be using it for the body may not know that the Brain Photobiomodulation Devices have been shown to help clear out toxic Alzheimer’s proteins.

Photobiomodulation Therapy on the Brain: Pioneering an Innovative Approach to Revolutionize Cognitive Dynamics
https://pmc.ncbi.nlm.nih.gov/articles/PMC11171912/
There’s one more therapy you may not have heard of, or may not know can not only heal your body but also assist your brain.
Curious?
Tune in next week…
P.S. Don’t forget to grab your free gift to plan a Purposeful Retirement…

Okay, I’ll leave you with that for now. Have a great rest of your day, and I look forward to seeing you next week.
Take care,
Nora
메타데이터
- post_id
- b4ea121c336b
- slug
- retirement-is-money-everything-b4ea121c336b-008-b4ea121c336b
- url
- https://medium.com/retirepluggedin/retirement-is-money-everything-b4ea121c336b-008-b4ea121c336b
- canonical_url
- https://medium.com/retirepluggedin/retirement-is-money-everything-b4ea121c336b-008-b4ea121c336b
- author_url
- https://medium.com/@nora_65031
- status
- ok
- fetched_at
- 2026-06-13 07:35:29